- Finance
- COVID-19
Status of Lending in the UK
With over 360 lenders in the UK, only 40 can offer the Coronavirus Business Interruption Loan Scheme (CBILS), this update takes a closer look at the non-CBILS lenders.
4 min read
Key takeaways
- CBILS lenders:
- Only 40 of over 360 UK lenders could offer the Coronavirus Business Interruption Loan Scheme.
- Tighter lending:
- Lenders asked for more information, tightened criteria and wanted security.
- Offers at risk:
- Existing offers could be withdrawn.
- Sectors off the table:
- Hospitality, travel, leisure and events were largely excluded.
- By Capitalise:
- A guest update from Capitalise on the lending market.
Now, more than ever, businesses are seeking financial support. Here we will keep you updated on the changing UK lending market.
For information on Coronavirus Business Interruption Loan Scheme, see Capitalise’ recent post What are CBILS loans? Here we explore what the loan is, who is eligible and how you can apply on the Capitalise Platform.
The UK lending market
Acceptance, interest rates and security
No longer business as usual
Additional information needed
Our panel of lenders are now asking for additional information. These include:
- The impacts and effects Covid-19 is having on the business
- What plans are in place to mitigate these impacts
- longer period of bank statements
- greater clarity in forecasts
Underwriting criteria tightening
Lenders are increasing their debt service coverage ratios. They are also reducing their appetite for refinancing existing debt.
Offers are not guaranteed
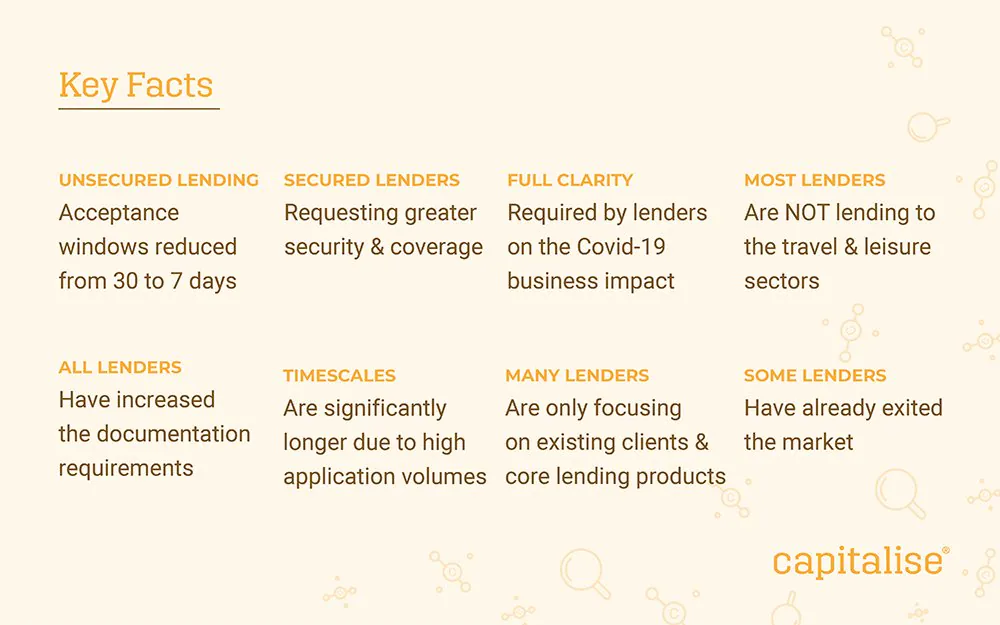
If businesses have an existing offer from a lender – these are at risk of being withdrawn by lenders. Whilst, typically lenders would hold these open for 30 days, we are seeing that lenders are reviewing their open offers and in some cases rejecting them.
iwoca have moved to 7 days and ESME to 14 days. We have also seen lenders pull offers entirely.
Security is a must
Our panel has also been moving offers away from unsecured lending backed by Personal Guarantee to fully secured. Market Finance have pulled out of unsecured loans and are focusing on their core invoice finance offering.
Revenue Lending
Our MCA panel has reduced the amount of debt they are willing to lend given their repayment is based on revenue through the merchant card terminal – in some cases, now this is zero.
Many sectors are off the table
Most lenders are not lending to the travel and leisure sector but we have now seen this loss of appetite for other business sectors heavily impacted by social distancing. These include:
- Hospitality and catering
- Travel
- Leisure
- Advertising and marketing
- Bars, restaurants, pubs, hotels
- Market stalls
- Event companies
Why are lenders so affected?
The economic contraction from Covid-19 and the government’s groundbreaking support packages, mostly notable the Coronavirus Business Interruption Loan Scheme (“CBILS”) run by the British Business Bank, will have a large impact on the current lending environment.
Regular lending will, in the UK, be hit by a demand-side shock, impacting business cash flow, and affecting the quantum of lending that will surpass their underwriting criteria. In addition to this, they will lose their competitive position as CBILS lenders’ supported interest holiday will make their facilities cheaper and more attractive. This, therefore, will allow the CBILS lenders to ‘cherry-pick’ the best and most secure businesses.
Non-CBILS lenders will have to balance these factors and make underwriting policy decisions which may have great consequences for their own businesses.
These lenders are lending. Affordability and security will be key – there will be a higher level of scrutiny through the credit process. Sectors such as travel, retail and hospitality are already facing restrictions, but there are solutions if SMEs and their advisers are nimble.
Capitalise works with over 100 lenders and we’ll keep adjusting our lender criteria to maximise acceptance rates as policies change. We are receiving updates from all our partners in banks, challenger banks, alternative lenders and the fintechs to help you understand what is happening day by day, minute by minute.
What can you do to help your clients
At Capitalise, we are constantly monitoring our 100 plus lenders and making sure we have the latest information from each lender. This can change day by day, however, our Covid-19 Business Support Hub will keep you updated on the latest information.
We can introduce you to a wider market and quickly, with your help we can find your clients the funding they need to continue if this is available in the market. If the funding is available in the market, we will know.
Complete a funding search through the platform as usual and your partnership manager and our funding specialists will help you every step of the way.
To find out more about Capitalise or explore more of their insights – visit their COVID-19 Support Hub: https://capitalise.com/covid19
Further reading
- Finance and support for your business GOV.UK
Find government-backed support and finance for business
- Set up a business GOV.UK
Choosing a legal structure when you're starting a business: the differences between being a sole trader and a limited company, including legal risk, registration and taxes.
- File your accounts and Company Tax Return GOV.UK
The official process and deadlines for filing statutory accounts and the CT600 with HMRC.